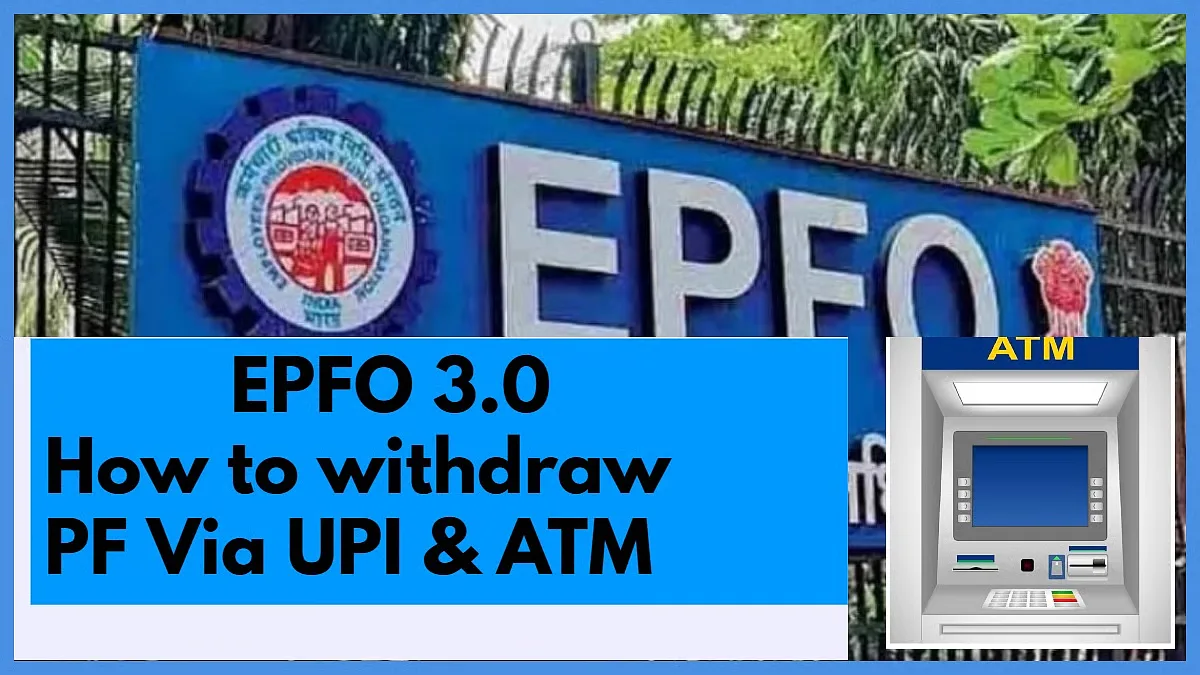
The Employees’ Provident Fund Organisation (EPFO) has officially initiated backend trials to integrate the Unified Payments Interface (UPI) directly with its Universal Account Number (UAN) portal. This flagship digital transformation—slated for a public launch by December 2026—will allow over 7.5 crore active contributing subscribers to claim up to 75% of their eligible provident fund balance instantaneously using payment apps such as BHIM, PhonePe, and Google Pay.
Under the ongoing pilot project conducted in partnership with leading public and private sector banking institutions, the Ministry of Labour and Employment aims to reduce claim settlement turnaround times from weeks to mere minutes for emergency liquidity needs.
The Technology Shift: Moving from Manual Claims to API-Driven Instant Payouts
Currently, accessing Provident Fund savings requires salaried employees to navigate the online UAN Portal, file claims through Form 31, 19, or 10C, and await multi-stage verification from employer desks and regional EPFO field offices. The existing verification hierarchy often causes delays ranging between 7 to 21 working days, posing critical challenges for subscribers facing sudden health crises, educational fee deadlines, or urgent home construction payments.
“The proposed UPI integration forms a cornerstone of the broader EPFO 3.0 digital framework, leveraging real-time NPCI settlement rails to automate claim validation against Aadhaar-linked bank accounts.”
By integrating NPCI-managed UPI handles directly with subscriber accounts, the new mechanism eliminates physical documentation and manual verification bottlenecks. EPFO is simultaneously architecting a dedicated mobile application designed to interface seamlessly with popular third-party UPI applications.
| EPFO 3.0: TRADITIONAL VS. UPI PAYOUT | |
|---|---|
| Feature | Details & Updates |
| Total Fund Corpus | ~₹26 Lakh Crore |
| Total Subscriber Base | >30 Crore (7.5 Crore Active Contributors) |
| Target Launch Window | By December 2026 |
| Maximum Withdrawal Limit | Up to 75% of Eligible EPF Balance |
| Mandatory Reserve | 25% Retained Minimum Balance |
| Primary Interface | Integrated UAN Portal & New Mobile App |
Key Withdrawal Rules and Minimum Corpus Safeguards
While the upcoming framework introduces unprecedented payout speed, strict regulatory parameters remain enforced to protect long-term retirement security. Subscribers must adhere to the following core compliance rules:
- 75% Partial Cap: Eligible subscribers can withdraw a maximum of 75% of their accumulated balance via the UPI mechanism for specified short-term needs.
- 25% Mandatory Retention: To preserve long-term compounding benefits, at least 25% of the total balance must remain intact in the EPF account, continuing to earn the official government-backed interest rate (currently 8.25% per annum).
- Aadhaar-NPCI Mapper Linkage: Instant payouts will only trigger if the subscriber’s UAN, Aadhaar, and primary bank account details match across national banking switch databases.
Analytical Perspective: Strategic Impact on India’s Financial System
The decision to plug a ₹26 lakh crore retirement pool into UPI infrastructure represents a massive evolution in public finance management. Historically, provident fund organizations treated liquidity as a restricted, friction-heavy utility to prevent early balance exhaustion. However, modern fintech adoption in India has altered user behavior, making instant access a standard expectation.
From a systemic standpoint, this move dramatically reduces administrative overhead for the EPFO administration. Handling millions of physical and portal-based claims annually creates huge operational expenditure. Automating simple partial withdrawals via UPI switches frees up institutional capacity to tackle complex pension cases, compliance tracking, and employer default audits.
However, financial planners warn that frictionless access carries structural behavioral risks. Easy withdrawal access via popular smartphone apps could tempt younger workers to treat their long-term retirement savings as short-term emergency funds, potentially eroding their terminal wealth compounding over multi-decade horizons.
Frequently Asked Questions (PAA)
When will the EPFO UPI withdrawal facility become operational for all members?
The EPFO UPI withdrawal service is currently in the trial phase with partner banks and is expected to launch formally by December 2026.
How much money can I withdraw from my PF account using UPI apps?
Subscribers can withdraw up to 75% of their eligible EPF balance, provided a minimum 25% mandatory reserve is retained in the account.
Which UPI apps will support direct EPFO PF money withdrawals?
Popular NPCI-linked payment platforms including BHIM, PhonePe, and Google Pay are planned to support direct payouts alongside EPFO’s upcoming dedicated mobile application.
Will full 100% PF balance withdrawal be allowed through UPI?
No, 100% balance withdrawal will not be permitted via UPI; members must retain at least 25% of their funds to earn ongoing interest and secure long-term retirement savings.
What prerequisites are required to use the upcoming instant UPI PF claim feature?
Subscribers must have an active UAN, an Aadhaar-seeded bank account, verified KYC documentation, and an active UPI ID mapped to the same registered mobile number.
Summary & Future Outlook
The integration of UPI payment rails into the EPFO ecosystem marks a major milestone in India’s digital public infrastructure. By removing administrative delays for partial withdrawals, the Ministry of Labour aligns retirement fund accessibility with modern banking standards. As pilot trials conclude across banking partners over the coming months, subscribers should ensure their UAN, Aadhaar, and bank account credentials are fully verified to take advantage of instant liquidity when the facility officially goes live by December 2026.

Manish Kumar began his professional journey in digital marketing and performance marketing, and currently works as a Digital Marketing Excutive and SEO expert. With over 3 years of professional experience, he handles both strategy and execution. Currently, he manages digital marketing and performance marketing at ‘Shabd Sanchi’ (shabdsanchi.com).